IBIT Options Price Calmer Swings Than Bitcoin's Rebound — SkimNews
Get the Finance newsletter
Daily finance — markets, central banks, M&A, the prints that move money. Free.
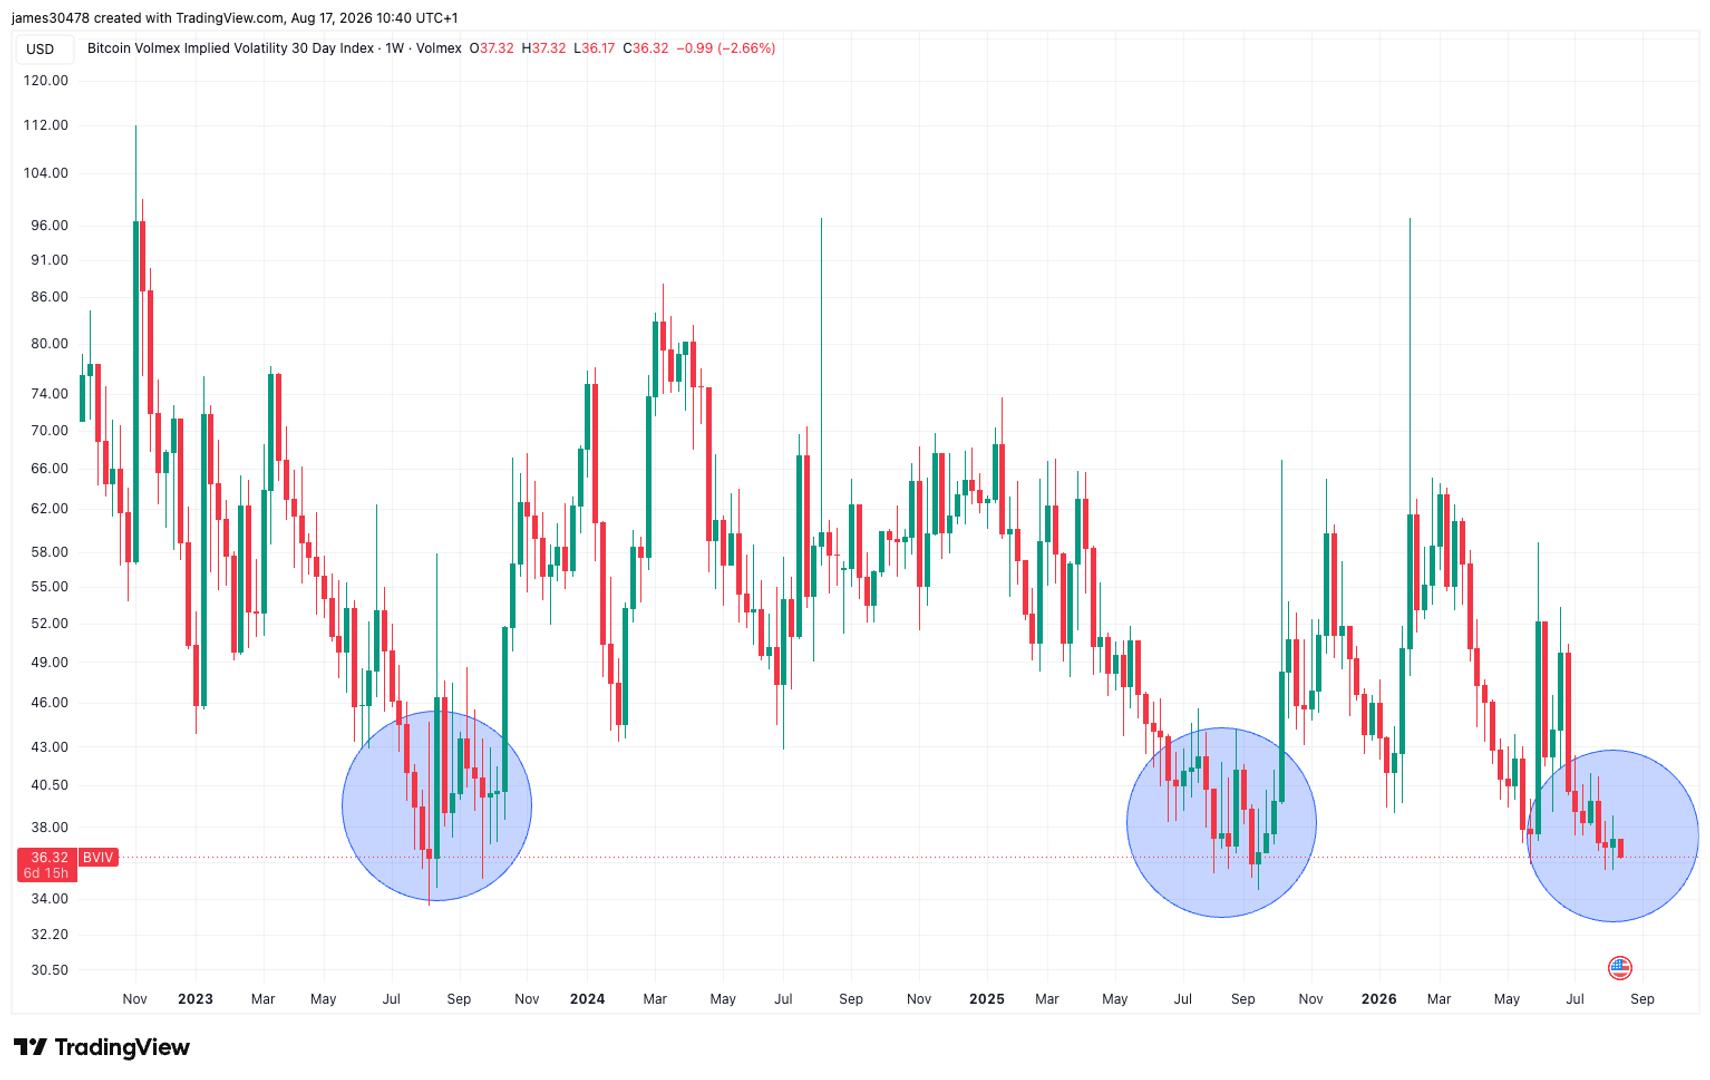
- IBIT's implied volatility stood at 37.4% versus realized volatility of 45.5% over the 20 trading sessions through Tuesday, per Saxo Bank options strategist Koen Hoorelbeke
- IBIT's implied volatility rank hit 11.9 based on Wednesday's data, placing the measure near the bottom of its 12-month range
- Saxo Bank concluded the options market is "pricing calmer conditions than the recent past produced," despite Bitcoin's sharp rebound
- Hoorelbeke identified resistance around $87,000 — where Bitcoin's advance stalled on Sept. 21 — and support between $76,000 and $77,000
- Bitcoin traded at $84,751 at the time of writing, up 1.6% in the prior 24 hours per CoinGecko
- Bitcoin ETF inflows slowed to $191 million even as a six-day streak reached $2.8 billion
Why it matters: With IBIT implied vol at 37.4% trailing 45.5% realized vol and an IV rank of 11.9 — near a 12-month floor — options traders are paying a fraction of what the recent price action would suggest is warranted. Anyone hedging a retest of Saxo's $76,000-$77,000 support zone gets unusually cheap puts, while sellers are essentially betting Bitcoin's wild swings are done.
Ask SkimNews