Bitcoin Options Stay Rich as Realized Vol Hits Year Low — SkimNews
Get the Finance newsletter
Daily finance — markets, central banks, M&A, the prints that move money. Free.
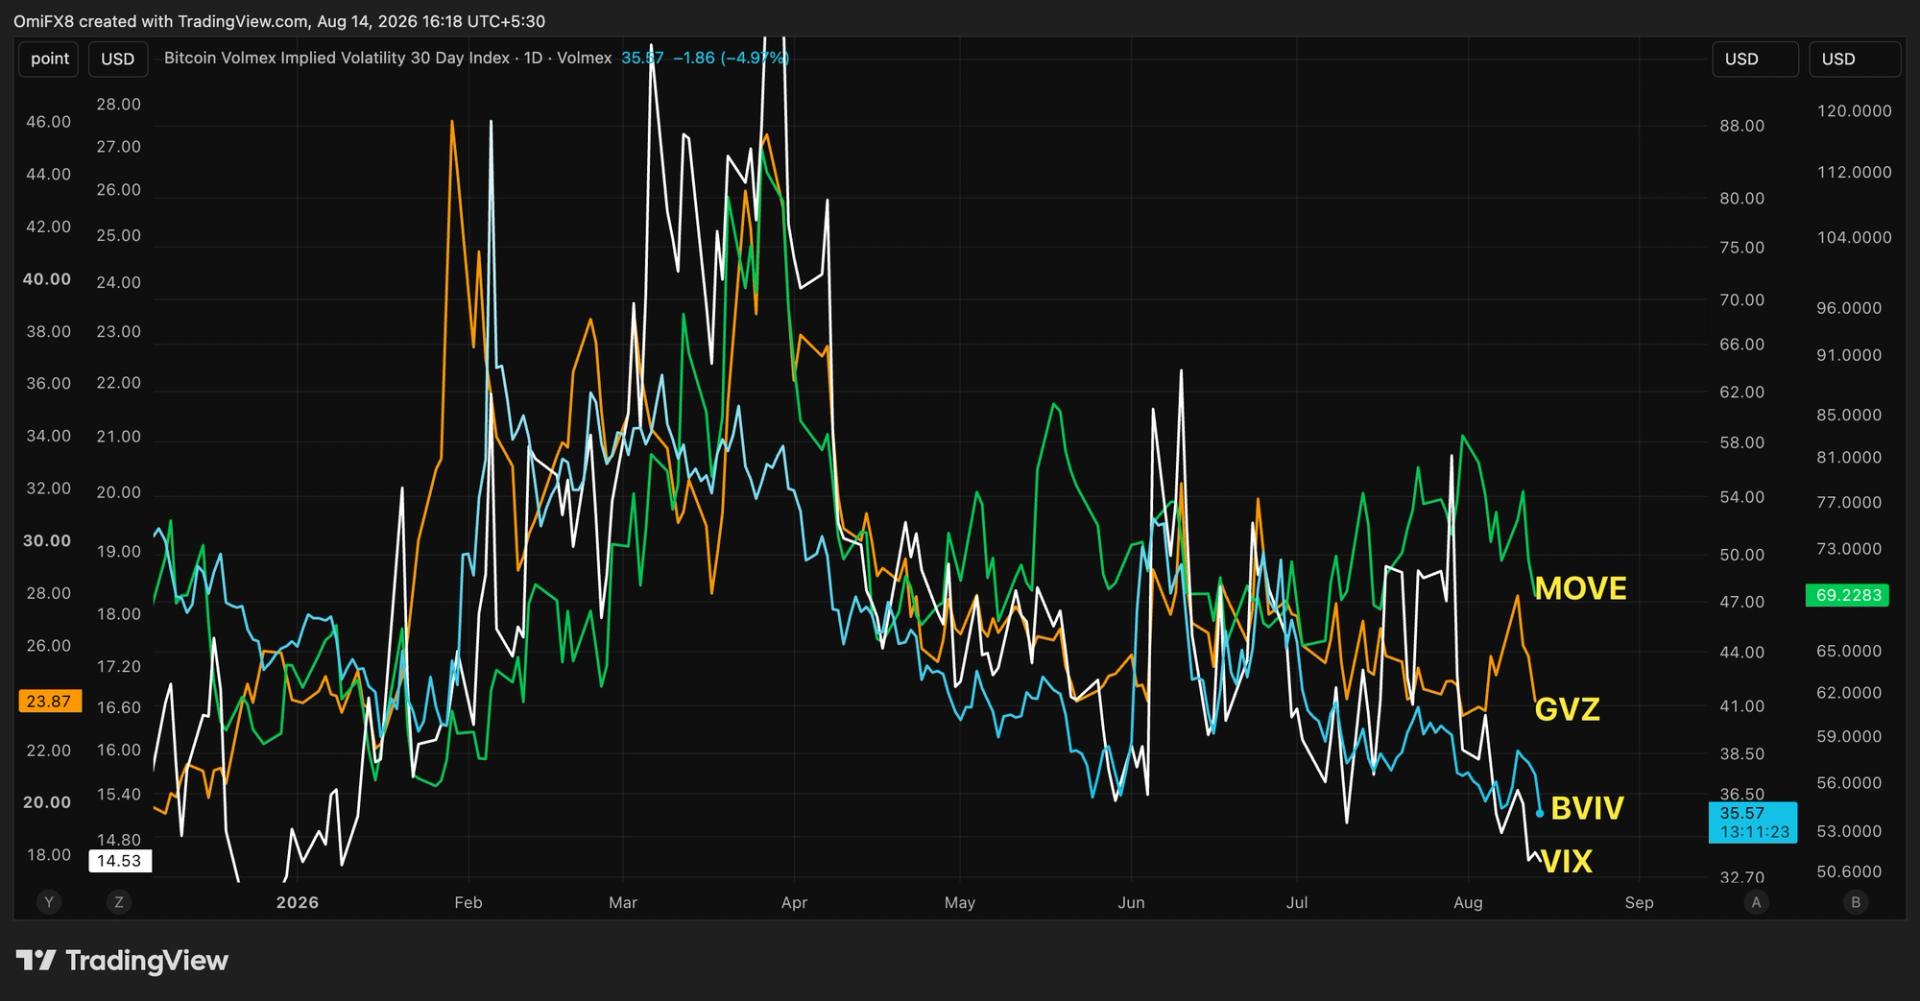
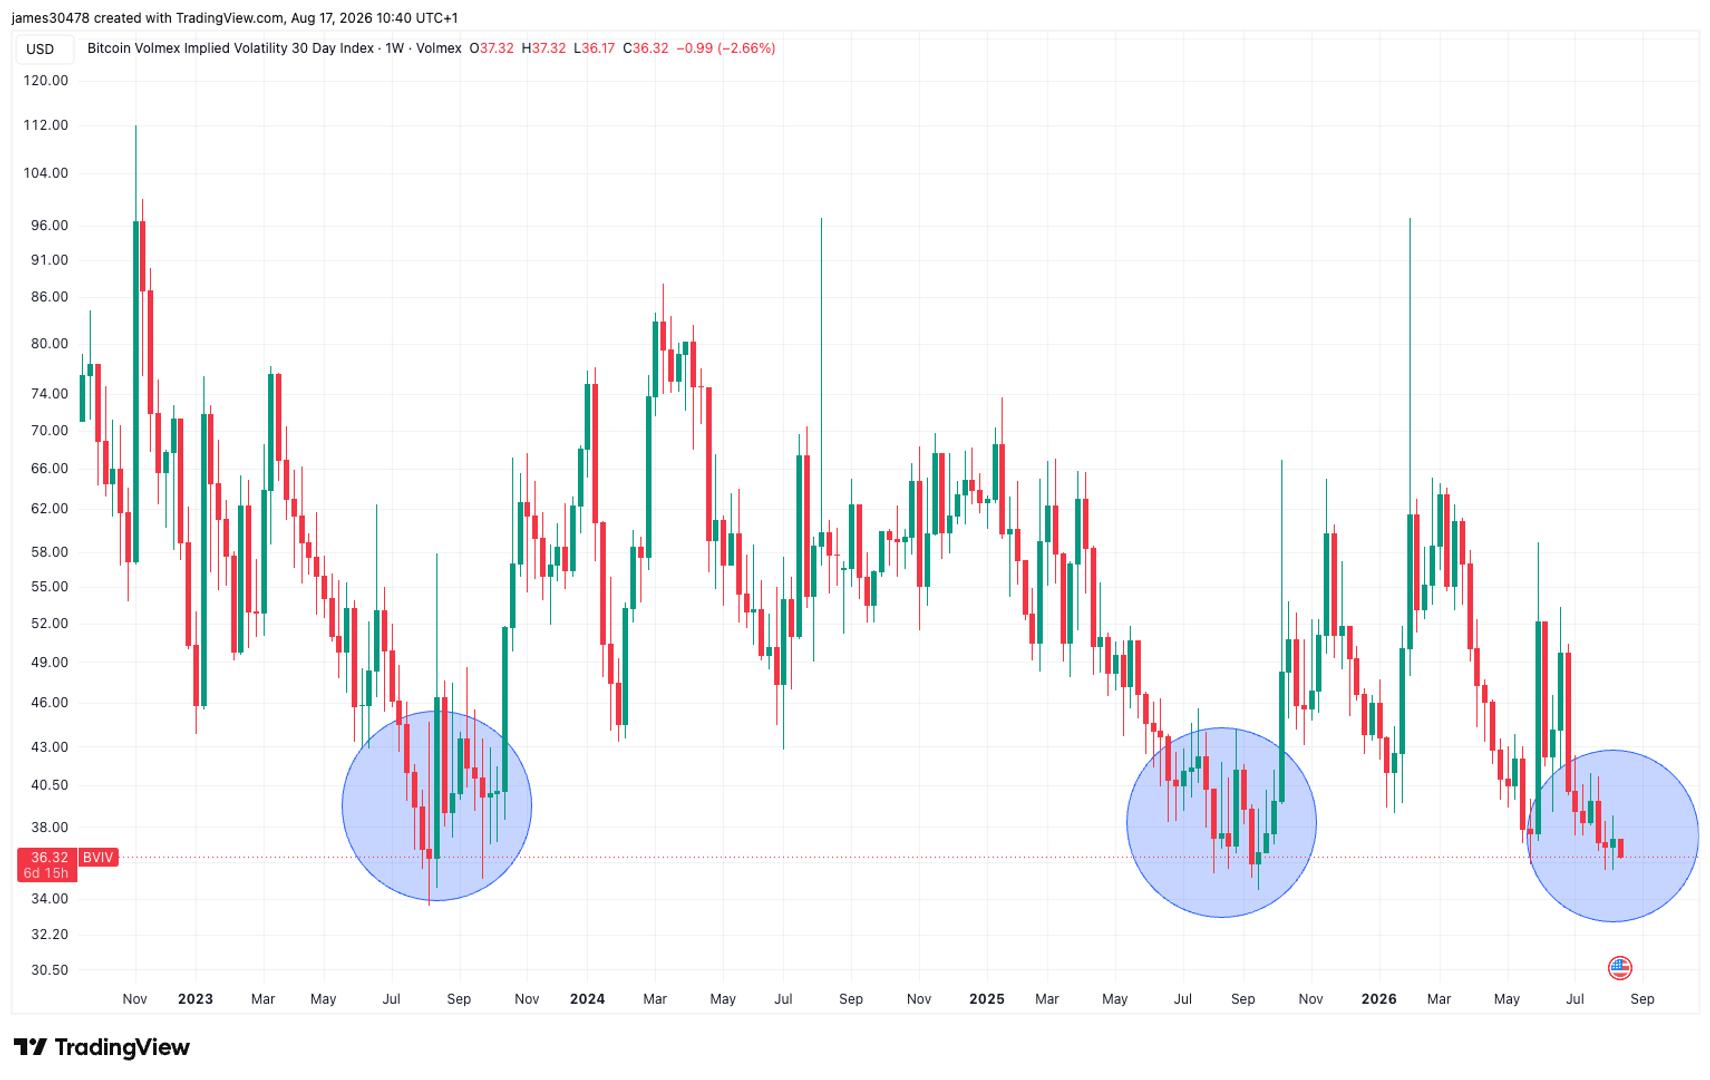
- Bitcoin's 30-day implied volatility of 36.35% sits about two-thirds higher than its realized volatility of 21.80%, with realized vol at its lowest since October 2025.
- Glassnode data puts one-week at-the-money implied volatility near 29% against realized volatility of roughly 16%, with the implied-versus-realized gap near a one-year high.
- The Volmex BVIV index, a forward-looking measure of expected volatility, currently sits at 36%, reinforcing that contracts are priced for substantially more movement than spot has delivered.
- Options buyers face a higher break-even bar: with rich premiums, BTC must move further than the recent calm suggests before calls or puts turn profitable.
- The setup favors options sellers, who collect inflated premiums while BTC remains range-bound — a disparity the source says is counterintuitive but explained by mean-reverting volatility.
Why it matters: The 36% implied vol versus 22% realized vol creates a trap for option buyers who assume quiet markets mean cheap protection. Sellers collect inflated premiums while BTC stays range-bound. Because volatility is mean-reverting, the next burst will prove the expensive options prescient — buyers need BTC to move further than the calm suggests just to break even.
Ask SkimNews