IBIT Options Underprice Recent Volatility, Saxo Finds — SkimNews
Get the Finance newsletter
Daily finance — markets, central banks, M&A, the prints that move money. Free.
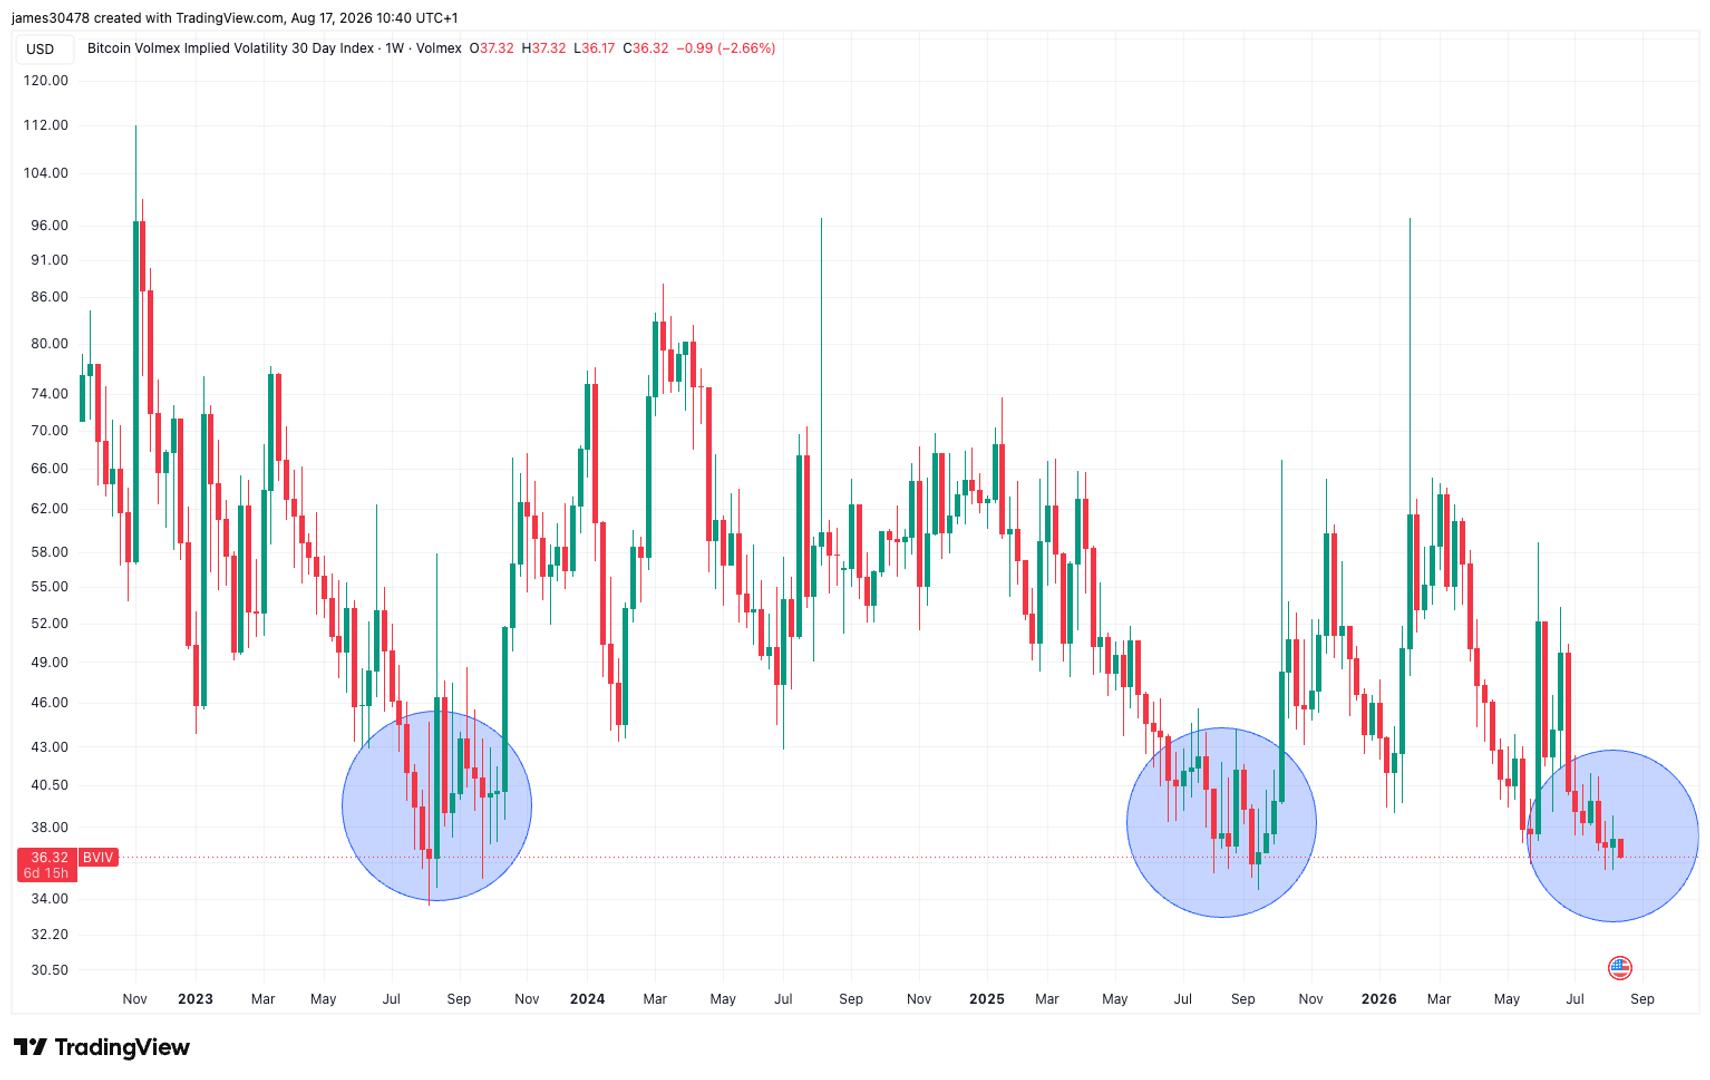
- IBIT implied volatility stood at 37.4% versus realized volatility of 45.5% over the 20 trading sessions through Tuesday, according to Saxo Bank's Koen Hoorelbeke.
- IBIT options priced an implied volatility rank of 11.9 on Wednesday — near the bottom of its 12-month range — meaning premiums are priced historically cheap relative to recent turbulence.
- Saxo Bank options strategist Koen Hoorelbeke identified Bitcoin resistance at $87,000 (where the advance stalled Sept. 21) and support between $76,000 and $77,000.
- Bitcoin traded at $84,751 at the time of writing, up 1.6% in the prior 24 hours per CoinGecko.
- Hoorelbeke concluded that "the options market appears to be pricing calmer conditions than the recent past produced," based on the gap between implied and realized volatility.
Why it matters: With IBIT's 45.5% realized volatility running 8.1 points above its 37.4% implied reading, options are pricing materially less turbulence than Bitcoin actually produced over the past 20 sessions. For Bitcoin ETF traders, that gap — combined with an IV rank of 11.9 near the floor of its annual range — means protective puts and calls are unusually cheap relative to the swings the underlying has already delivered.
Ask SkimNews